
Impact of Interest Rates on Naples Home Prices and Trends
In October 2026, average U.S. 30-year fixed mortgage rates moved above 7%, putting pressure on buyers’ purchasing power. That’s a key part of the impact of interest rates on the Naples housing market: higher borrowing costs can slow decisions and temper demand, but they don’t erase it. Naples’s median sale price was down 0.089% year over year for the three months ending October 2026.
It’s understandable to associate higher mortgage rates with softer home prices, but rates are only one factor. National demand, available homes, and local conditions all influence how buyers and sellers respond. That’s why Naples may not move in lockstep with broader trends.
This article explains how mortgage rates affect affordability and buying activity, and how national demand and Florida’s local conditions shape home prices in Naples. You’ll see why prices can change even when rates move in the same direction, and which market signals help put those changes in context.
Table of Contents
What is the housing market like in Naples today?
Mortgage rates shape what buyers can finance, not just what a home costs. In October 2026, average U.S. 30-year fixed rates moved above 7%. The impact of interest rates on the Naples housing market starts with this shift in purchasing power.
Affordability pressures are especially relevant to first-time buyers. Nationally, they accounted for 31% of home transactions in September 2026. In Naples and Collier County, households earning below $100,000 face significant difficulty finding a property. Buyers weighing a purchase need to consider how the mortgage payment fits their finances, alongside other ownership costs.
Inventory affects negotiating leverage. Active inventory in the Naples metro was down 19% year over year in the article’s look-ahead discussion. Yet the market isn’t moving at one speed: homes spent a median of 132 days on the market in October 2026, and Naples homes averaged two offers over the three months ending that month. Buyers can request seller concessions or walk away when a property’s value doesn’t align with its price.
Regional searches also shape demand across Southwest Florida. Between April and June 2026, 56% of Naples homebuyers searched within the Naples metropolitan area, while 44% searched to move out. Buyers comparing Naples with Bonita Springs, Estero, Marco Island, or Fort Myers may weigh location, property type, and budget differently. Those priorities influence which homes compete for their attention.
New construction offers another path for buyers. In Naples, new homes add inventory and help establish benchmarks for pricing and features. When comparing a new build with a resale, weigh location, features, and purchase terms alongside financing costs. Higher rates can prompt buyers to pause, while lower rates may make financing more feasible. Understanding the impact of interest rates on the Naples housing market also means considering inventory and each property’s value, not rates alone.
Naples home prices and year-over-year trends
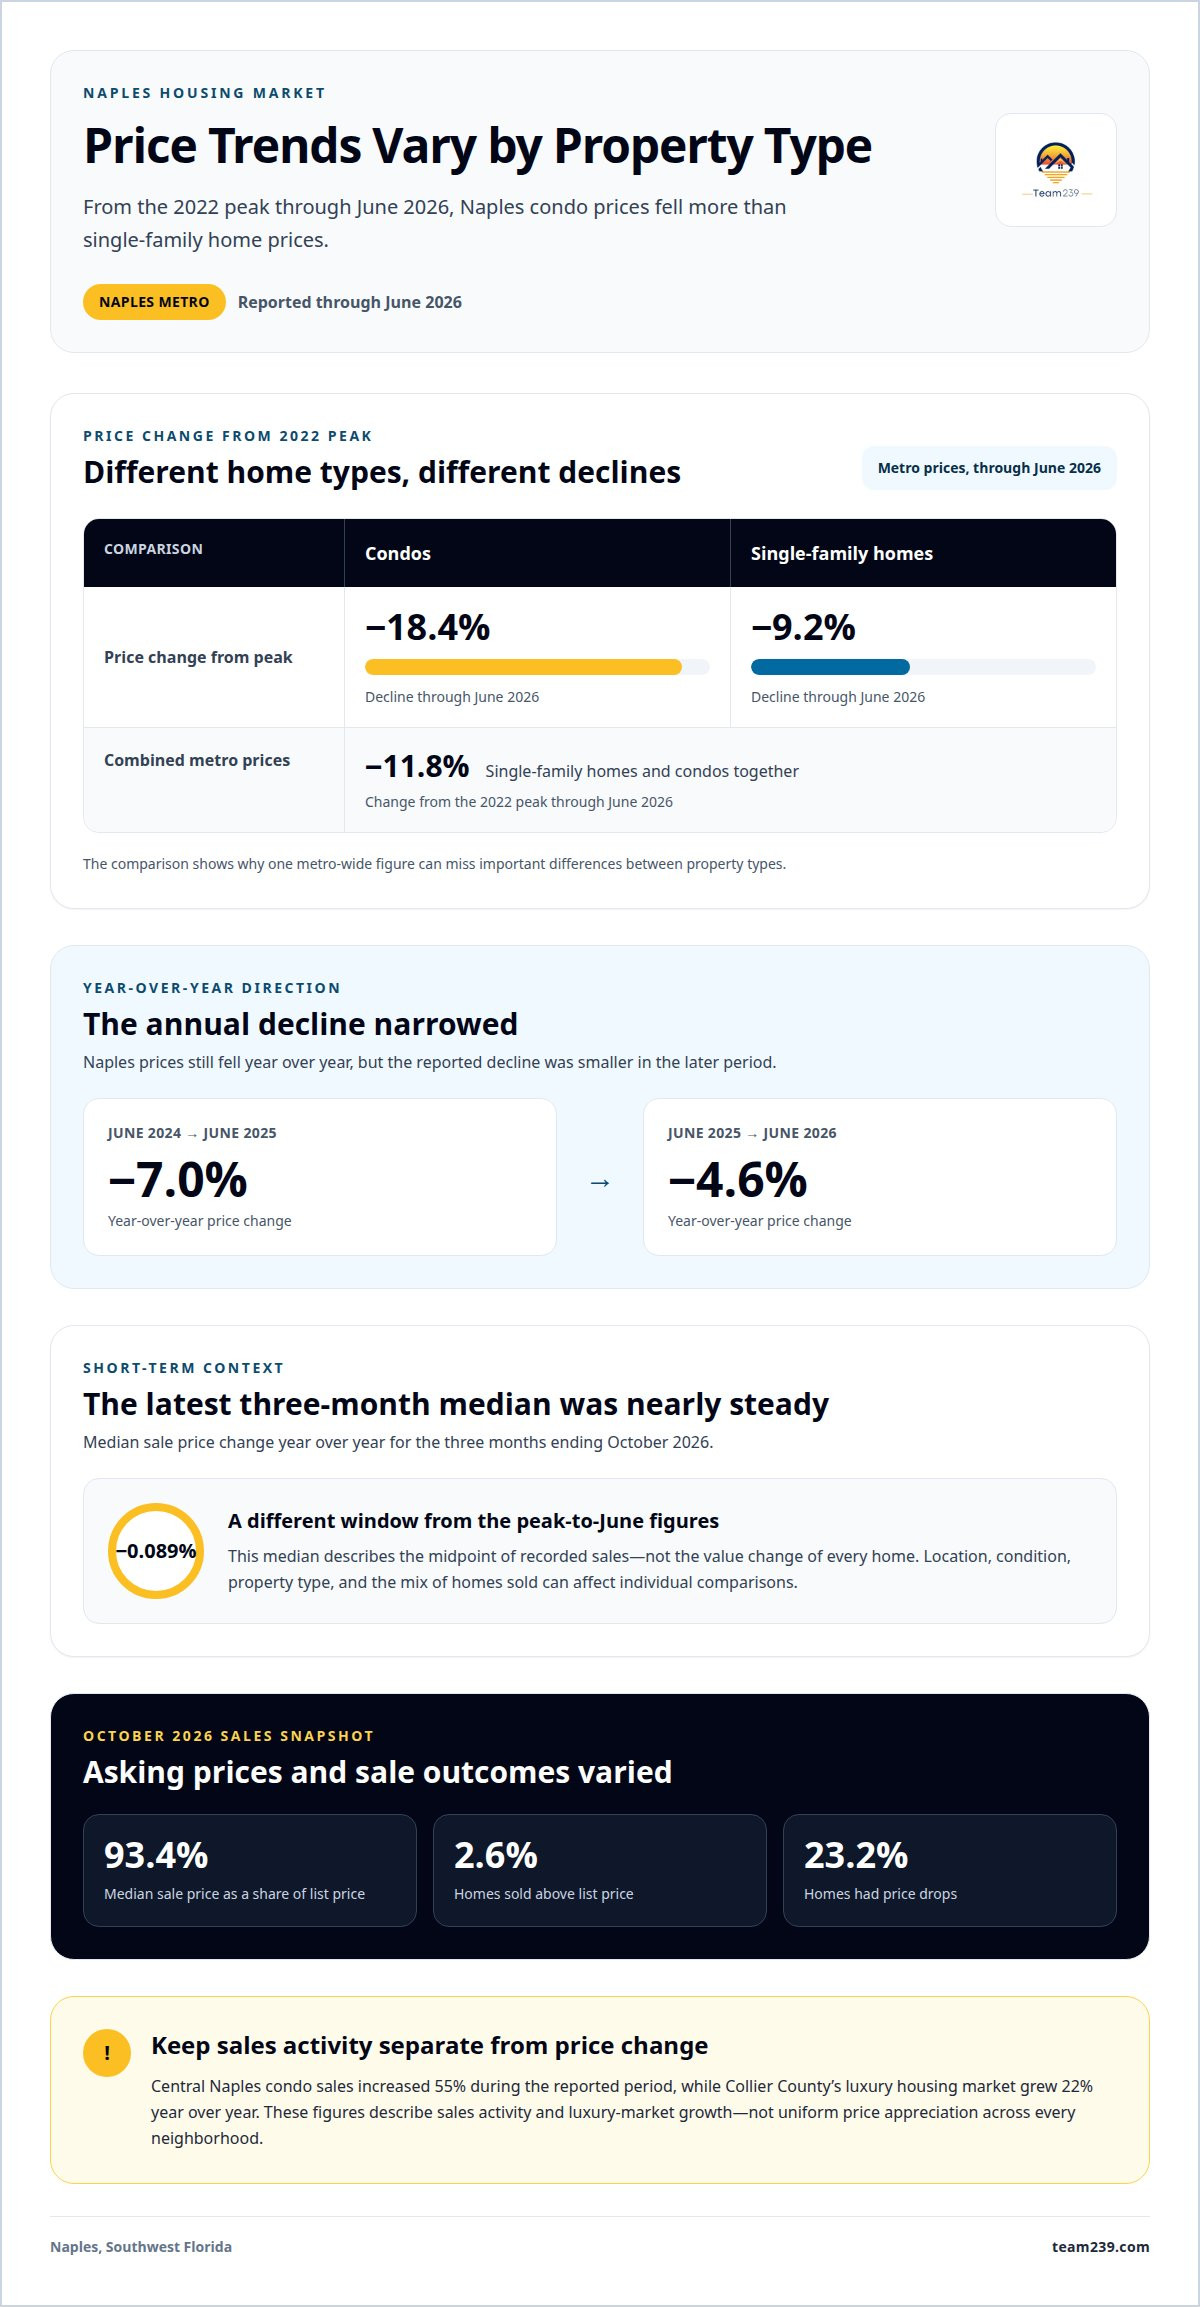
Naples prices have eased from their 2022 peak, but declines vary by property type. Through June 2026, metro prices for single-family homes and condos were down 11.8%. Condo prices fell 18.4%, while single-family home prices declined 9.2%. The year-over-year change also narrowed: prices fell 7.0% from June 2024 to June 2025, then 4.6% from June 2025 to June 2026. These trends show why a single market-wide figure can miss important differences.
For the three months ending that month, the median was down 0.089% year over year, pointing to relative short-term stability in that measure. A median describes the midpoint of recorded sales, not the value of every property. Location, condition, property type, and the mix of homes sold can all shape how individual prices compare.
Negotiating conditions offer another view. Naples homes sold for a median of 93.4% of list price in October 2026, while 2.6% sold above list. In the same month, 23.2% of homes had price drops. Together, these figures suggest that most sales did not exceed asking price, though outcomes still differed by listing. Buyers can use a property’s condition and comparable sales to assess whether its asking price fits.
Regional trends also diverge. Central Naples condo sales increased 55% during the reported period, while Collier County’s luxury housing market grew 22% year over year. Those figures describe sales activity and luxury-market growth, not uniform price appreciation across every neighborhood. Family homes and condos may follow different patterns, so local comparisons are more useful than applying one county-wide trend to every property.
For a clearer pricing strategy, sellers should weigh recent comparable sales, property type, and current listing competition together. A median can provide context, but it cannot replace an assessment of a specific home. Sellers considering Naples residential resale representation can use these market differences to inform a property-specific listing approach.
National economic conditions and housing demand
National financing conditions shape how many buyers can qualify and what they can afford in Naples. The average U.S. 30-year fixed mortgage rate was 6.86% in September 2026. The National Association of Realtors’ Housing Affordability Index was 105.4 that month, down from 106.7 in September 2025. Rising rates can temper demand by increasing borrowing costs, while stronger economic growth can support buyer confidence.
Sales data show that demand and supply move together, but not always in sync. U.S. existing-home sales rose 1.5% month over month in September 2026, reaching an annual rate of 3.99 million, yet remained 2.2% below the year-earlier level. Existing-home inventory stood at 1.60 million, or 4.8 months of supply. For Naples, national trends provide context, while local listings and buyer activity determine negotiating conditions.
Higher rates can make financed condo purchases harder to carry, contributing to softer demand and price pressure. Naples metro condo prices were down 18.4% from their 2022 peak through June 2026, but that decline cannot be attributed to mortgage rates alone; property type and local supply also matter.
Luxury and waterfront demand can respond differently from the broader market. In Naples, demand for luxury homes often outpaces supply. In Collier County, sales priced at $1 million or more accounted for nearly 30% of closed sales and 70% of total dollar volume. These figures show why high-end demand can remain resilient even as financing costs challenge some buyers.
When rates rise or fall, Naples buyers and sellers should consider financing costs alongside comparable properties, inventory, and the likely buyer pool. Buyers can revisit their budget and priorities; sellers can compare their home with competing listings and current demand. Rates can shift purchasing power, but they don’t determine a home’s value on their own.
How have interest rates affected Naples home prices and sales in recent years?
Mortgage rates and Naples prices moved through sharply different phases. Florida’s 30-year mortgage rate was 3.10% in 2021, while the reported rate was 7.11% in 2026. From December 2019 to June 2022, Naples metro home prices rose 74%. That surge occurred during a low-rate period, but rates alone don’t explain price growth. Demand, available homes, and changing buyer preferences also shaped the market.
Prices later adjusted as financing became more expensive and market conditions changed. Through June 2026, Naples prices for single-family homes and condos were down 11.8% from their 2022 peak. The sequence matters: low borrowing costs can support purchasing power, while higher rates can reduce what financed buyers can afford. Price changes reflect that pressure alongside local supply and property-specific factors.
Sales activity shows why rate changes don’t translate into a simple stop-start market. Naples recorded 197 home sales in October 2026, up 1.9% year over year. More sales in that month can coexist with prices below a previous peak. A transaction count measures activity, while sale prices reflect which homes sold and the terms buyers accepted.
Cash purchases can also soften the direct effect of mortgage rates on some transactions. Cash buyers represented 27% of U.S. home transactions in September 2026. That national figure doesn’t establish the share in Naples, but it illustrates why mortgage rates affect financed buyers differently from cash buyers. In Naples, demand can therefore remain active even when borrowing costs limit some buyers’ budgets.
For a practical comparison, buyers can assess how financing costs affect their budget, then compare suitable homes by location, condition, and recent sale activity. Sellers can track local competition and buyer response rather than assuming a past peak sets today’s value. Discuss how rate shifts shape your Naples property strategy before choosing your next move.
Team239
Team239 helps buyers and sellers connect changing rates with Naples market conditions and their next property decision. If you’re buying, the team can help weigh financing considerations against available resale homes or new construction. Sellers can use local market context to shape a strategy for a residential resale or luxury listing. Relocation Consulting can also help people assess how Naples fits their move and housing priorities.
Turn to Team239 when you’re ready to compare property options, plan a sale, or make a move informed by local trends. The right next step depends on your goals, preferred property type, and timing. Contact Team239 to discuss your Naples real estate plans.
Make your next Naples move with a clear strategy
Understanding the impact of interest rates on the Naples housing market is less about predicting the next rate move and more about choosing a strategy that fits your goals. Before deciding whether to buy or sell, clarify your preferred property type, timing, and financing priorities. Use those criteria to evaluate opportunities as local conditions change.
Team239 can support that next step through Residential Resale Representation, New Construction Buyer Representation, and Luxury Property Listing Services. The right approach depends on whether you’re purchasing, listing, or comparing property options. A focused conversation can help connect your plans with the Naples market context you’ve explored here.
Contact Team239 to discuss Naples real estate and take your next step with a strategy shaped around your goals.
Frequently Asked Questions
What are current mortgage rates for homebuyers in Naples, Florida?
There isn’t a separate mortgage rate set just for Naples; rates generally track national mortgage markets, while each borrower’s quote depends on loan details. In October 2026, average U.S. 30-year fixed rates moved above 7%, and Florida’s reported 30-year rate was 7.11% in 2026. Those figures provide context, not a personalized offer. Loan terms and borrower qualifications can change the rate offered.
How do mortgage rates affect housing demand and inventory in Naples, Florida?
Higher mortgage rates can reduce the number of financed buyers who can meet their target payment, potentially slowing offers and extending the search or sale process. Rates don’t directly determine how many homes owners list. For a useful Naples comparison, track inventory by property type and price range: conditions for condos may differ from those for single-family homes. Similar local comparisons matter in Bonita Springs, Estero, Marco Island, and Fort Myers.
How do interest rates affect affordability for Naples homebuyers?
A higher rate increases borrowing costs for the same loan amount, so a buyer may need to lower their budget or put more cash toward the purchase. Compare loan scenarios using the same down payment and loan term to see how payments change. Include recurring ownership expenses, such as taxes and insurance, when setting a comfortable budget.
How do mortgage rates influence cash buyers and luxury home sales in Naples?
Cash buyers aren’t directly affected by mortgage-rate changes because they aren’t financing the purchase with a home loan. Rates can still affect their competition: if borrowing becomes harder for other buyers, the mix of offers may shift. In Naples luxury sales, location, condition, and the availability of comparable homes also shape buyer interest and negotiations.
How does the Naples housing market compare with other Florida markets as rates change?
Florida recorded 11 consecutive months of year-over-year gains in closed single-family home and condo sales through July 2026. That statewide trend doesn’t mean every local market moved identically. For comparisons across Naples, Bonita Springs, Estero, Marco Island, and Fort Myers, consider local sales and inventory by property type rather than treating statewide activity as a direct forecast for each community.
All content provided on the Naples Florida Real Estate Channel and other associated social media platforms is for informational/entertainment purposes only. The owner of Naples Florida Real Estate makes no representations as to the accuracy or completeness of any information on this site or found by following any link on this site. Information provided is subject to change, please consult Kristin and Jonathan directly or another licensed real estate agent to receive the best expertise for your specific situation. The owner of Naples Florida Real Estate will not be liable for any errors or omissions in this information nor for the availability of this information. The owner will not be liable for any losses, injuries, or damages from the display or use of this information.
What are forecasts for mortgage rates and the Naples housing market?
A National Association economist estimated that a drop in mortgage rates from 7% to 6% would bring 576 additional buyers to Naples and Marco Island. Lower rates could make financing more feasible and spur activity, while higher rates may temper demand without eliminating it.
Comments