
What Is an Escalation Clause in Real Estate Florida? 2026 Guide
An escalation clause can win you a home in a competitive bidding war, or it can hand the seller your maximum budget on a silver platter. If you want to know what is an escalation clause in real estate Florida, you likely understand the frustration of losing out on a property you love, balanced against the dread of overpaying well beyond appraised value. It is a razor-thin line. In high-demand pockets across the state, submitting an offer without the right legal guardrails can quickly jeopardize your financing and put your earnest money deposit at risk.
You don't have to gamble when multiple bids hit the table. In this guide, you'll master how official Florida Realtors escalation addenda function under FAR/BAR contracts, how to enforce legitimate proof requirements for competing offers, and how to defend your purchase price with precise appraisal gap strategies. We break down the core legal mechanics, evaluate when to deploy this tool versus a clean highest-and-best offer, and walk through practical steps to protect your bottom line from start to finish.
Table of Contents
What Is an Escalation Clause in Florida Real Estate?
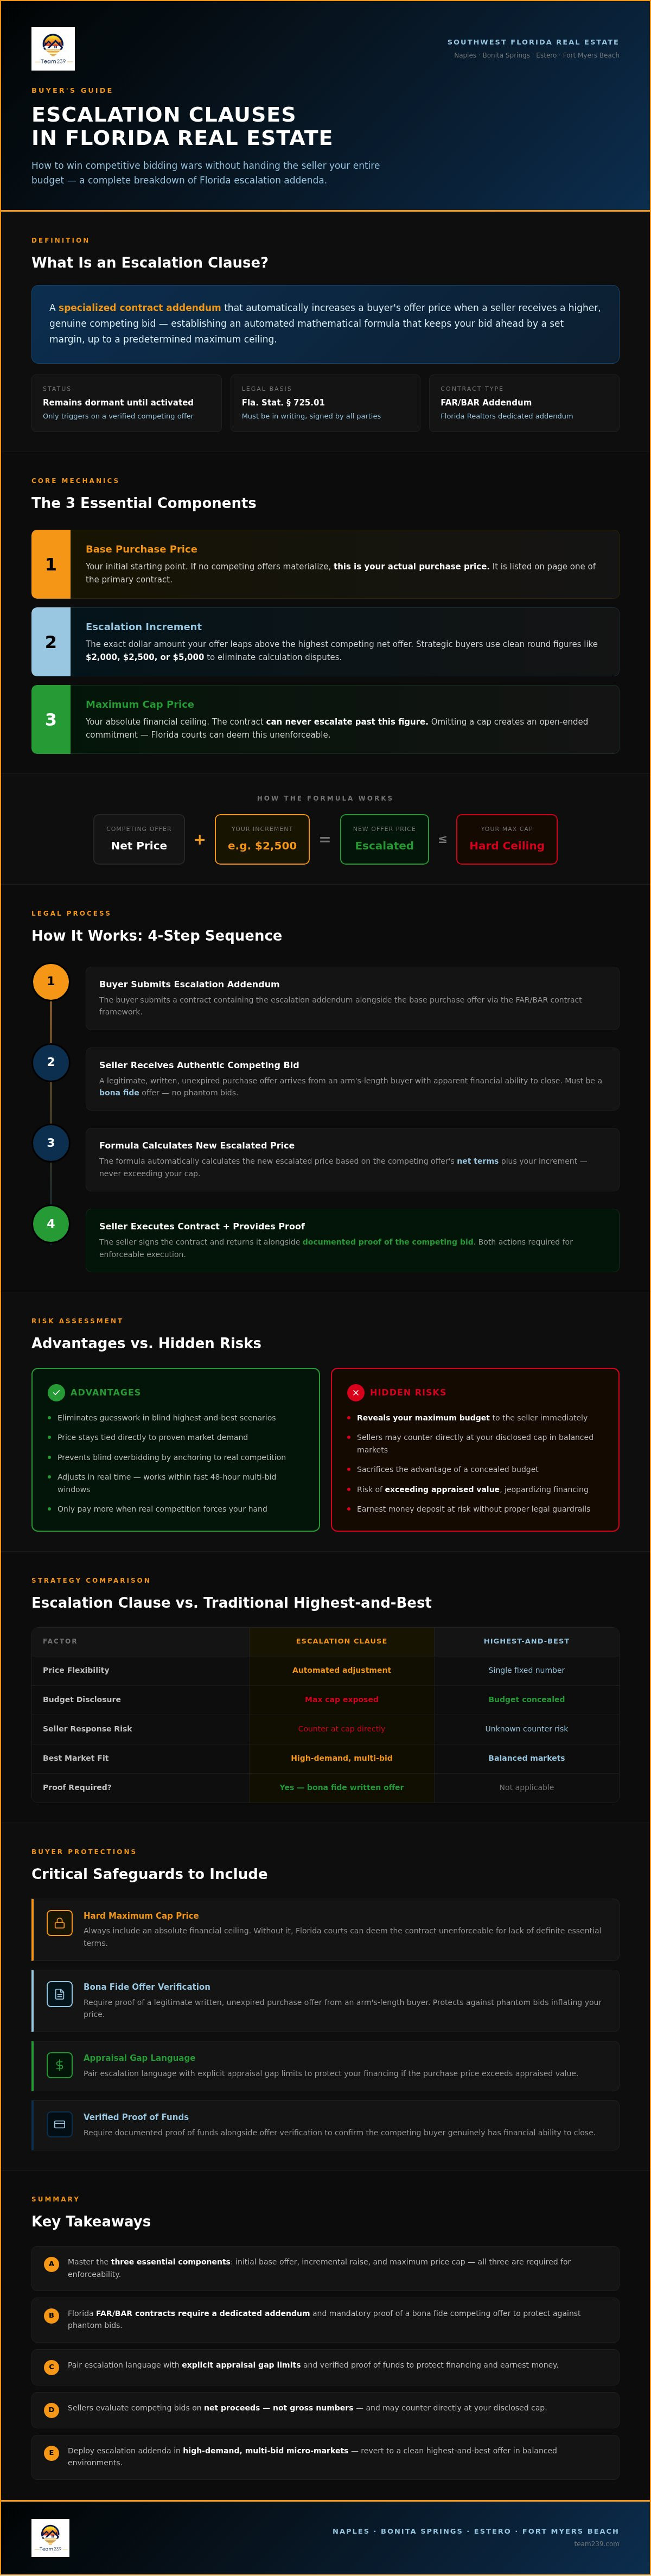
When buyers ask what is an escalation clause in real estate Florida transactions, they are looking for a competitive edge without writing a blank check. Simply put, an escalation clause is a specialized contract addendum that automatically increases a buyer's offer price when a seller receives a higher, genuine competing bid. Rather than guessing what rivals might offer, you establish an automated mathematical formula that keeps your bid ahead by a set margin, up to a predetermined maximum ceiling.
Traditional negotiations rely on static pricing. You submit a figure, wait for a seller counteroffer, and go back and forth. In fast-paced markets, however, multiple bids can arrive within 48 hours. That dynamic makes standard bargaining too slow. Florida escalation addenda solve this friction by adjusting terms in real time. Under Florida contract principles, this tool remains dormant unless activated by a verified, bona fide written offer from another purchaser. Drawing on the foundational escalation clause definition, this addendum guarantees that you only pay more when real competition forces your hand.
The Core Mechanics of Escalation Addenda
A legally sound escalation addendum hinges on three interdependent structural components:
Base Purchase Price: Your initial starting point. If no competing offers materialize, this is your actual purchase price.
Escalation Increment: The exact dollar increment your offer leaps above the highest competing net offer, such as $2,000 or $5,000.
Maximum Cap Price: Your absolute financial ceiling. The contract can never escalate past this figure, preserving your budget and protecting your earnest money.
Escalation Clauses vs. Traditional Highest and Best Offers
When listing agents encounter heavy interest, they often set a deadline for traditional highest-and-best offers. In a blind submission, you pick a single fixed number and hope you didn't overpay or fall short by a few hundred dollars. An automated escalation clause eliminates that guesswork. It keeps your price tied directly to proven market demand.
Yet tactical risks remain. Including an escalation clause reveals your cards. Sellers immediately see your maximum ceiling, even if your base offer sits lower. In balanced market environments, sellers frequently bypass the automated formula entirely and counter your offer directly at your top cap. Understanding what is an escalation clause in real estate Florida means recognizing that while it prevents blind overbidding, it also sacrifices the advantage of a concealed budget.
How Does an Escalation Clause Work Under Florida Contract Law?
Executing an escalating purchase offer requires strict adherence to Florida contract principles. Under Florida Statute of Frauds (Fla. Stat. § 725.01), agreements conveying real property must be in writing and signed by all parties to remain enforceable. An escalation clause operates through a disciplined four-step sequence. First, the buyer submits a contract containing an escalation addendum. Second, the seller receives an authentic competing bid that exceeds the buyer's base price. Third, the formula calculates the new escalated price based on the competing offer's net terms. Finally, the seller executes the contract and returns it alongside proof of the competing bid. As highlighted in Cornell Law School's legal overview of escalator clauses, the enforceability of these contractual mechanisms relies entirely on clear objective formulas and definite price parameters.
The Three Essential Components of the Clause
To avoid contract ambiguity, every addendum requires three definite metrics:
The Base Offer: The starting purchase price detailed on page one of the primary contract.
The Escalation Increment: The exact amount added above a competing bid. Strategic buyers use clean, round figures like $2,500 or $5,000 to eliminate awkward calculation disputes.
The Maximum Price Cap: The absolute ceiling. Omitting a cap creates an open-ended financial commitment, which Florida courts can deem unenforceable for lack of definite essential terms.
Bona Fide Offer Verification and Florida Disclosure Rules
A triggered escalation requires a bona fide competing offer. Under Florida transaction standards, this means a legitimate, written, unexpired purchase offer from an arm's-length buyer who possesses the apparent financial ability to close. Informal verbal inquiries or non-binding letters of intent cannot trigger an escalation.
To protect buyers against phantom offers manufactured to artificially trigger the cap, the Florida Realtors Escalation Addendum mandates complete disclosure. The seller must deliver a complete, signed copy of the competing offer to the buyer. While sensitive personal buyer information like tax numbers or banking details may be redacted, purchase prices, concession credits, and closing timelines must remain visible for verification before the higher price locks in.
FAR/BAR Contract Compatibility and Legal Considerations
A common misconception when researching what is an escalation clause in real estate Florida is expecting to find a pre-printed checkbox on standard contracts. Neither the FAR/BAR Standard Contract nor the FAR/BAR "AS IS" Contract contains built-in escalation text. Real estate licensees cannot draft custom legal provisions from scratch without risking the unauthorized practice of law.
Instead, agents must use the standardized Florida Realtors Escalation Addendum or language prepared by a Florida Bar real estate attorney. Precision matters when crafting these terms. When competing for high-value properties and exploring Naples Florida homes for sale, partnering with an experienced advisory team like Team239 ensures your contract language protects your deposit while presenting a compelling offer to sellers.
Pros, Cons, and Hidden Risks of Florida Escalation Clauses
Weighing the strategic advantages against tactical downsides is vital when learning what is an escalation clause in real estate Florida transactions. This addendum shields buyers from overpaying in blind bidding wars, yet it introduces significant financing liabilities. Before committing legal terms to paper, you need to understand both the offensive leverage and the defensive exposures embedded in automated formulas.
Buyer Advantages in Multiple-Offer Environments
Automated increments prevent you from making unnecessary financial leaps. Rather than impulsively submitting your top figure to outbid an unknown competitor, the formula tethers your price directly to substantiated market activity. If rival bids fall well below your ceiling, you secure the property at a lower, incremental price. That capped structure gives you complete control over your financial boundaries while signaling to the seller that you mean business.
The Seller Leverage Trap: Exposing Your Maximum Budget
Revealing your price cap compromises your negotiating position. When a seller reviews your offer, you hand them your ceiling upfront. Listing agents frequently capitalize on this transparency. Instead of waiting for another offer to trigger your formula, the seller can simply reject your addendum and issue a direct counteroffer at your maximum cap.
This tactic strips away your leverage. The seller knows exactly what you are willing to spend on the home. Many sellers also favor clean, traditional contracts over conditional formulas that require disclosing competitor bids. As outlined in Freddie Mac's homebuyer guide on escalation clauses, exposing that ceiling without securing a binding agreement can leave buyers vulnerable to aggressive counter-pricing.
Appraisal Gaps and Financing Contingency Complications
A triggered escalation price does not mean the property will appraise at that higher value. Lenders base their mortgage commitments entirely on independent appraisals, not the outcome of a neighborhood bidding war. If your base offer of $600,000 escalates to $640,000, but the appraiser values the property at $615,000, an immediate $25,000 appraisal shortfall occurs.
Without an explicit appraisal contingency or an agreed appraisal gap clause, the buyer must make up that cash difference out of pocket or risk defaulting on their earnest deposit. In competitive South Florida luxury enclaves, sellers often demand partial or full appraisal gap coverage alongside an escalation addendum to ensure the deal closes. When calculating these risks and planning your transition while moving to Southwest Florida, aligning your liquid reserves with your contract contingencies is essential to keep your transaction secure.
Seller Perspective: How Florida Homeowners Should Handle Escalation Offers
Receiving an offer with an automated formula gives sellers immediate leverage, but it also introduces operational friction. Understanding what is an escalation clause in real estate Florida from the seller's vantage point means evaluating net certainty rather than celebrating an inflated top-line number. A high headline figure attached to fragile financing terms can easily stall your closing.
Evaluating the Total Offer Package Beyond Purchase Price
The highest escalated dollar figure is not automatically your best contract. A financed offer that escalates to $850,000 with a minimal earnest money deposit and an appraisal contingency presents serious risk of deal failure. Conversely, a clean, non-escalating cash bid at $835,000 with a five-day inspection period and zero financing hurdles often delivers higher net proceeds and guaranteed closing certainty.
Before entertaining an escalating bid, demand immediate written verification. Inspect the buyer's proof of liquid funds to confirm they can handle both the escalated purchase price and any resulting appraisal shortfalls. Scrutinize their inspection timelines and closing date flexibility to see if the overall terms match your personal schedule.
Strategic Response Options for Florida Sellers
Florida homeowners faced with an escalation addendum hold three distinct strategic pathways:
Option 1: Accept and Trigger the Formula. Accept the escalation terms by providing a bona fide competing offer. Ensure sensitive competitor information is redacted while showing clear net pricing.
Option 2: Counter at the Cap Directly. Reject the complex addendum entirely. Issue a straightforward counteroffer at or near the buyer's revealed maximum cap price on standard contract terms.
Option 3: Call for Highest and Best. Set a firm deadline requiring all interested parties to submit their single best, fixed-price offer without conditional escalation riders.
Protecting Seller Net Proceeds and Closing Certainty
Triggering an escalation addendum obligates you to share a rival buyer's purchase contract. Under Florida real estate licensing rules and national ethical standards, listing agents must obtain written permission from the seller before disclosing any competing terms. Ensure names, account numbers, and personal identifiers are cleanly redacted to maintain transactional confidentiality.
Guarding your net bottom line means preventing post-inspection renegotiations or appraisal fallout down the road. For tailored pricing methodologies and proven listing workflows, explore our detailed breakdown on how to sell my home in Naples, Florida. If you are preparing to list your luxury residence, partner with Team239 to evaluate multiple offers and negotiate terms that maximize your net return.
Strategic Best Practices: When to Use an Escalation Clause in Florida
Timing dictates success when deploying contractual formulas. Understanding what is an escalation clause in real estate Florida transactions is only half the equation; knowing when to deploy one separates winning bids from blown negotiations. In balanced market environments, using an escalation addendum indiscriminately can weaken your position by signaling your ceiling to a seller who had no competing interest in the first place.
Ideal Scenarios for Deploying Escalation Clauses
Escalation riders deliver tangible leverage when specific market conditions align:
Sub-72-Hour Multiple Bidding Wars: Properties entering the market with rapid tour volume and verified competing written offers benefit immediately from automated increments.
Rare Waterfront and Prime Neighborhood Listings: Turnkey properties in high-demand communities often generate emotional demand where comparable sales lag behind buyer interest.
Buyers with Strong Liquid Reserves: When you possess the cash capacity to absorb appraisal gaps above standard mortgage limits, an escalation clause keeps you in control.
When to Avoid Escalation Clauses in Florida Deals
Never submit an escalation addendum on properties with extended days on market. If a home has sat active for several weeks without competing contracts, introducing an escalating range simply tells the seller you are willing to spend more than your base offer. They can reject the rider and counter you at the top number without providing any competing proof.
Avoid using them if your financing is tightly leveraged. Without surplus cash to cover appraisal variances, an escalated contract can fall apart during underwriting, leaving your escrow deposit in dispute. Builders also operate under completely different rules. Production and custom home builders rely on uniform contract formats and fixed baseline pricing, making escalation riders ineffective when evaluating new construction homes in Bonita Springs.
Partnering with Experienced Southwest Florida Real Estate Professionals
Mastering what is an escalation clause in real estate Florida requires hyper-local execution. Team239 structures protective contract language across Naples, Bonita Springs, and Marco Island, balancing aggressive purchase ceilings with precise contingency safeguards. We analyze active inventory patterns, track neighborhood-level absorption rates, and vet listing agent response tendencies to determine whether an escalating formula or a clean, fixed offer creates the winning advantage. Ready to secure your next property with tactical precision? Contact Team239 for strategic guidance on Southwest Florida real estate.
Take Command of Your Next Florida Real Estate Negotiation
Navigating competitive bidding wars doesn't require reckless overspending. Truly understanding what is an escalation clause in real estate Florida empowers you to set disciplined financial boundaries, automate competitive price increments, and enforce strict proof standards for competing offers. When properly paired with explicit appraisal gap limits, this contractual addendum safeguards your earnest money while positioning your bid to win.
Success in Southwest Florida's luxury enclaves requires localized market intelligence and tactical contract drafting. Backed by the statewide reach and local strength of MVP Realty Associates, LLC, Team239 brings decades of combined residential transaction experience across Naples, Bonita Springs, and Estero. We know how to structure terms that protect your capital while capturing a seller's full attention. Connect with Team239 to craft a winning real estate negotiation strategy and approach your next property purchase with total clarity and confidence.
Frequently Asked Questions
Is an escalation clause legal in Florida real estate contracts?
Yes, escalation clauses are fully legal in Florida real estate contracts. Under Florida contract law and the Statute of Frauds, all terms and amendments modifying purchase prices must be in writing and signed by both parties. While legal, the clause must contain clear mathematical formulas and definite price limits to remain enforceable. Agents cannot draft custom legal provisions from scratch, requiring standardized association forms or attorney drafting.
Does the Florida Realtors/Florida Bar (FAR/BAR) contract have a standard escalation clause?
No, standard FAR/BAR residential purchase contracts do not include a pre-printed escalation clause. Instead, Florida Realtors provides a standalone Escalation Addendum to Contract form that attaches directly to the FAR/BAR Standard or "AS IS" agreements. If this official addendum is not used, a licensed Florida Bar attorney must draft custom contract rider language to avoid the unauthorized practice of law.
Can a seller simply counter-offer at my escalation cap price without proof of another bid?
Yes, sellers have full legal authority to reject the escalation formula entirely and issue a direct counteroffer at your maximum cap price. Submitting an escalation addendum reveals your pricing ceiling upfront. If you are learning what is an escalation clause in real estate Florida, remember that disclosing your cap gives listing agents leverage to negotiate directly at your top dollar without validating a competing offer.
What proof must a Florida seller provide to trigger an escalation clause?
Under the standard Florida Realtors Escalation Addendum, a seller must deliver a complete, unexpired copy of a legitimate competing written offer. The competing contract must represent a bona fide arm's-length transaction. While personal identifiers such as the rival buyer's tax numbers or bank accounts are redacted, the purchase price, seller concessions, and closing dates must remain visible to verify the net escalation formula.
What happens if a home does not appraise for the escalated purchase price?
If an appraised valuation falls below the escalated purchase price, the lender will only base mortgage financing on the lower appraised figure. Unless you included a specific appraisal gap guarantee or retain an appraisal contingency in your Florida contract, you must cover the cash difference at closing, renegotiate the price with the seller, or exercise your contingency rights to cancel the contract and reclaim your deposit.
Can I use an escalation clause if I am getting a mortgage loan?
Yes, financed buyers can use escalation clauses, but listing agents will scrutinize your financing pre-approval carefully. In competitive markets like Naples and Bonita Springs, sellers often demand proof of liquid cash reserves demonstrating that you can bridge potential appraisal shortfalls. Lenders enforce strict loan-to-value limits, meaning your escalated cap must align with your total verified borrowing capacity and cash assets.
Why do some Florida listing agents dislike escalation clauses?
Many listing agents dislike escalation addenda because they complicate offer comparisons and create administrative burdens regarding offer disclosures. Evaluating varying financing terms, concessions, and net proceeds across multiple escalation formulas takes significant time. Agents often prefer straightforward highest-and-best submission deadlines where buyers submit their single cleanest, non-conditional price, eliminating disputes over competing offer legitimacy.
Can a seller accept another offer even if my escalation clause offered a higher price?
Yes. Florida sellers are never legally obligated to accept the offer with the highest gross price. When analyzing what is an escalation clause in real estate Florida, keep in mind that sellers weigh the complete contract package. An all-cash bid with zero contingencies or a guaranteed quick closing often nets a seller more certainty than a higher, financed offer burdened by an escalation rider and appraisal risks.
Comments